Understanding Pension Pillars and Retirement Savings in Romania
Moving to Romania, you quickly realize that while the scenery is stunning and the culture vibrant, navigating the administrative labyrinth can feel like a full-time job. One of the biggest puzzles for many expats is understanding the local pension system and how their hard-earned contributions will eventually translate into retirement security. This guide is here to unravel the complexities of Romania's multi-pillar pension framework, offering a realistic, empathetic roadmap for foreigners looking to build a stable future here.
The Romanian Pension System: A Bird's Eye View for Expats
When you first start working in Romania, whether as an employee or a self-employed professional, you'll notice contributions being deducted from your salary or income for social security. This isn't just a simple payment; it's the foundation of your future pension. For many of us, especially those coming from countries with very different systems, it can be incredibly confusing to figure out where that money goes and what it actually means for our retirement. It’s not just one big pot, but rather several distinct "pillars" working together, each with its own rules and implications.
Why Understanding the Pillars Matters
Understanding these pillars isn't just about administrative compliance; it's about empowerment. Without a clear grasp of how your pension is structured, you can't effectively plan your retirement, assess your future income, or make informed decisions about supplementary savings. For expats, this is even more critical, as you might have pension entitlements in multiple countries, and knowing how Romania's system integrates, or doesn't, with those can significantly impact your financial outlook. Ignoring it simply means leaving a big part of your financial future to chance, and trust me, you don't want to find yourself surprised years down the line.
The Core Principles of Romania's Pension Framework
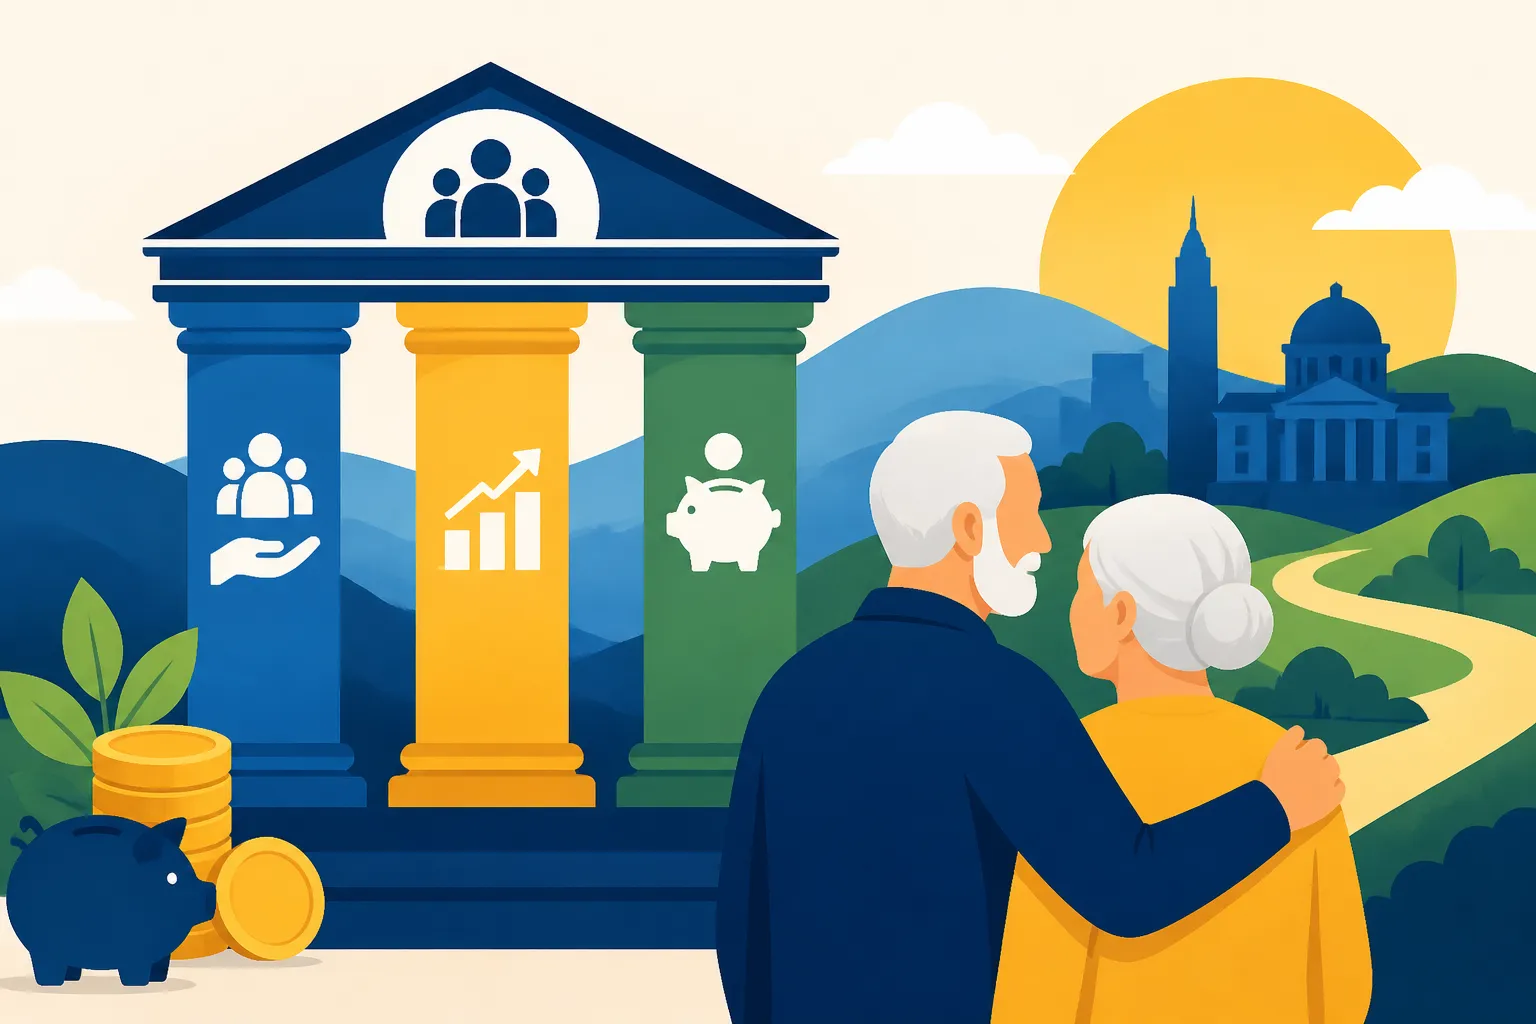
Romania's pension system is designed around three main pillars, mirroring a model seen in many European countries. The idea is to diversify risk and provide multiple layers of retirement income, rather than relying solely on the state. Pillar I is the traditional, pay-as-you-go public system, mandatory for all employed individuals. Pillar II is a mandatory, privately managed fund system, where a portion of your social contributions goes into a personal investment account. Finally, Pillar III consists of voluntary, privately managed funds, offering an additional layer of savings for those who want more. Each pillar serves a distinct purpose, and together, they form the safety net and investment strategy for your golden years here.
Pillar I: The Public, State-Funded Pension Scheme
This is the big one, the bedrock of the Romanian pension system, officially managed by Casa Națională de Pensii Publice (CNPP). Often referred to as the "state pension" or the "public pension," Pillar I operates on a pay-as-you-go basis, meaning current workers' contributions fund the pensions of current retirees. It’s a system many of us are familiar with from our home countries, where your contributions don't sit in a personal account, but rather flow directly to support the previous generation. For expats, it can feel a bit abstract, especially if you only plan to be here for a few years, but your contributions are still very real and count towards potential future benefits.
Who Contributes and How Much?
If you're legally employed in Romania, contributions to Pillar I are mandatory. A significant portion of your gross salary, specifically part of the social insurance contribution (CAS – Contribuția de Asigurări Sociale), goes towards this pillar. Currently, the standard CAS rate is 25% of your gross salary, which covers both Pillar I and Pillar II. The employer withholds this amount and pays it on your behalf. For the self-employed, like those operating as a PFA (Persoană Fizică Autorizată), you are also required to contribute CAS, usually based on a chosen income level, often at least the gross national minimum wage. It's crucial to understand these contributions are not optional, and ensuring they are paid correctly is vital for your future eligibility. You can find a comprehensive breakdown of these charges in our guide to Understanding Social Contributions (CAS and CASS) in Romania: The Full Guide.
Eligibility and How Benefits are Calculated
To be eligible for a Pillar I state pension, you need to meet certain criteria related to your contribution period and age. The standard retirement age in Romania is currently 65 for men and is gradually increasing for women, aiming to reach 63 by 2030. You also need a minimum contribution period, usually around 15 years, to qualify for a partial pension, with a full pension requiring a longer period, often around 35 years. The actual pension amount is calculated based on a complex formula that considers your total contribution period, your gross earnings throughout your working life (which are indexed), and a "pension point" value set by the government. Essentially, the more you've contributed and the longer you've worked, the higher your potential pension will be. This system aims to ensure a degree of fairness, but the actual purchasing power of these pensions is always a subject of public debate and can be a concern for long-term planning.
Challenges and Future Outlook for Pillar I
Like many state pension systems globally, Romania's Pillar I faces its share of challenges. Demographic shifts, such as an aging population and declining birth rates, put pressure on the pay-as-you-go model. Fewer active workers are supporting an increasing number of retirees, which can lead to calls for reforms, whether that means raising the retirement age, increasing contributions, or adjusting pension benefits. Expats might also worry about the long-term stability and value of such a system. While the government regularly attempts reforms to ensure sustainability, predicting the exact state of Pillar I decades from now is, naturally, impossible. This uncertainty is precisely why the other pillars and personal savings become so important for a truly secure retirement.
Pillar II: The Mandatory Private Pension Funds
Moving beyond the state-managed system, Pillar II is where things start to feel a bit more like a personal investment for your retirement. This pillar, known as Pilonul II or Fonduri de Pensii Private Obligatorii (Mandatory Private Pension Funds), was introduced to provide an additional, funded component to your pension. It’s a crucial distinction from Pillar I, as the money here is invested on your behalf by private administrators, aiming to grow your retirement pot over time. If you're employed or self-employed and contributing CAS, a portion of that contribution is automatically diverted here, making it mandatory for eligible individuals.
The Automatic Enrolment and Fund Selection Process
When you start working in Romania, if you're under a certain age (typically around 35 for automatic enrolment), a portion of your CAS contributions is automatically directed to a Pillar II fund. You usually have a window, often a few months after starting employment, to choose your preferred private pension fund administrator. If you don't actively choose one, you'll be automatically assigned to an administrator by the pension authority (ASF – Autoritatea de Supraveghere Financiară). These administrators, like BCR Pensii, Metropolitan Life, or NN Pensii, are regulated and compete to manage your money, offering different investment strategies – though generally, these funds are conservative, focusing on long-term growth with managed risk. It’s worth doing a little research, even if you’re automatically assigned, to understand where your money is going and if you want to switch to a different fund that might align better with your long-term goals.
Understanding Your Statements and Investment Growth
Once you're enrolled in a Pillar II fund, your chosen administrator will send you periodic statements, usually annually. These statements are vital, even if they sometimes feel like they're written in a language only an actuary could love. They detail your contributions, the performance of your fund, and the total value of your accumulated assets. Think of it as a statement for a long-term savings account that also invests. The goal of these funds is to grow your money through investments in a diversified portfolio, including government bonds, equities, and other financial instruments. While the growth might seem slow and steady, especially in the early years, the power of compound interest over decades can lead to a substantial sum by the time you retire. Don't just file these statements away; try to understand them, as they represent a tangible part of your retirement wealth.
Portability and Transferring Funds for Expats
A common question for expats is what happens to their Pillar II funds if they leave Romania or if they already have pension funds in other countries. The good news is that these are your personal funds. While you generally can't withdraw them before retirement age (except in very specific, limited circumstances, like permanent incapacity), they remain invested. If you move to another EU country, there might be provisions for transferring pension rights under EU regulations, although direct fund transfers between specific Pillar II funds and foreign pension schemes are not straightforward. It's more likely that your Romanian Pillar II funds will be paid out to you at retirement, wherever you are, or consolidated with other benefits. If you're concerned about managing funds across borders, especially for receiving potential pension payments in the future, services like Wise offer efficient ways to handle international transfers, minimizing fees and ensuring transparent exchange rates. This flexibility is a significant advantage over the purely state-funded Pillar I, giving you more direct ownership over a part of your retirement savings.
Pillar III: Voluntary Private Pension Funds and Individual Savings
Beyond the two mandatory pillars, Romania's pension system offers a third, entirely voluntary option: Pillar III. This pillar, known as Pilonul III or Fonduri de Pensii Facultative (Voluntary Private Pension Funds), is for those who want to actively save more for retirement and take advantage of additional tax benefits. It’s essentially a long-term investment vehicle designed specifically for retirement savings, managed by private companies under the supervision of the ASF, similar to Pillar II. For expats looking to bolster their retirement nest egg beyond what the mandatory systems provide, Pillar III can be a very attractive option.
Why Consider Pillar III for Enhanced Retirement Security
The primary reason to consider Pillar III is to supplement your income from Pillars I and II. While the mandatory pillars provide a foundation, they might not be enough to maintain your desired lifestyle in retirement, especially if you have an international lifestyle or higher financial goals. Pillar III offers more flexibility in terms of contribution amounts and fund choices, allowing you to tailor your savings more precisely. Furthermore, contributions to Pillar III often come with tax advantages, such as being tax-deductible up to a certain annual limit (currently 400 Euros per year) from your taxable income. This means you can reduce your immediate tax burden while saving for the future. For expats, this can be a smart move, especially if you plan to stay in Romania long-term and want to leverage local financial instruments for your overall retirement strategy.
Choosing a Voluntary Fund and Contribution Flexibility
Unlike Pillar II, where you are automatically enrolled, Pillar III requires you to actively choose a fund and sign a contract with a private pension administrator. There are several reputable administrators in Romania, many of whom also manage Pillar II funds, such as BRD Pensii, Generali Pensii, and Aegon Pensii. When choosing a fund, you’ll typically find more diverse investment options compared to the more conservative Pillar II funds. Some Pillar III funds might offer a higher exposure to equities for potentially greater growth, while others remain more balanced. You can contribute as much or as little as you want, though there's usually a minimum monthly contribution. The beauty here is the flexibility: you can adjust your contributions based on your financial situation, pause them if needed, and restart when you're able. This adaptability makes Pillar III a versatile tool in your broader financial planning toolkit.
Other Private Savings Vehicles: A Look Beyond Pensions
While Pillar III is specifically designed as a pension product, it's certainly not the only way to save for retirement. Many expats also consider other private savings vehicles to complement their pension planning. These can include:
- Investment Funds: Mutual funds, ETFs (Exchange Traded Funds), and direct stock investments offer more direct control over your investment strategy and risk profile. However, they typically don't offer the same specific tax benefits as Pillar III pensions and might require more active management or professional advice.
- Bank Savings and Deposits: While low-yield, these offer liquidity and capital protection, suitable for short-to-medium term savings or an emergency fund, rather than long-term retirement growth.
- Real Estate: Investing in property, either residential or commercial, can be a way to generate rental income or capital appreciation. However, it's a significant investment with its own complexities, including property taxes and maintenance.
- Life Insurance with a Savings Component: Some life insurance policies offer an investment element that builds cash value over time, which can be accessed later.
Diversifying your retirement savings across multiple avenues can offer greater security and flexibility. For complex scenarios involving multiple international investments, consulting with a financial advisor who understands cross-border taxation and investment regulations is almost always a good idea.
Navigating Pension Rights as an Expat in Romania
One of the trickiest aspects of retirement planning for expats is piecing together pension rights from various countries. If you've worked in Romania and also in your home country or other EU/non-EU states, your retirement picture is likely a mosaic, not a single clear image. Understanding how these pieces fit together, or sometimes don't, is paramount. Romania's place within the EU and its bilateral agreements with other nations play a huge role here.
Social Security Agreements and Cross-Border Considerations
For EU citizens, the situation is relatively straightforward thanks to EU social security coordination regulations. Your periods of insurance, employment, or residence in different EU member states are "totalized" – meaning they are added together – to determine your eligibility for a pension. So, even if you haven't accumulated enough contribution years in Romania alone, your years in other EU countries can count towards meeting the minimum requirement. Each country where you've contributed will then pay a proportional pension based on the periods you worked there. For non-EU citizens, it's more complex. Romania has bilateral social security agreements with a limited number of non-EU countries. If your home country has such an agreement with Romania, similar totalization rules might apply. If not, you might have separate pension entitlements in Romania and your home country, requiring you to claim each independently. It's a patchwork that requires careful attention to detail and, often, a lot of patience.
How to Track Your Contributions and Pension Statements
Keeping tabs on your pension contributions is absolutely vital, but it can feel like a chore in Romania. For Pillar I, you can request a history of your contributions from the Casa Națională de Pensii Publice (CNPP). This record, called a carnet de muncă or sometimes a adeverință de vechime, is crucial for verifying your eligibility and future pension calculation. For Pillar II and Pillar III funds, your private pension administrator is legally obliged to send you annual statements detailing your contributions and the fund's performance. Always keep these documents safe! If you ever lose track or have questions, reaching out directly to your fund administrator or the CNPP is the first step. Be prepared with your CNP (Personal Numeric Code) and any relevant identification documents, as these are your keys to accessing your information. It's also a good idea to know How to Get Your CNP (Personal Numeric Code) for Healthcare Access in Romania as it is a fundamental identifier for almost all administrative processes, including pensions.
Planning Your Retirement: Combining Romanian and Foreign Pensions
The ultimate goal for many expats is to retire comfortably, regardless of where their contributions originated. Combining Romanian and foreign pensions requires a strategic approach. Start by getting a clear picture of your entitlements from each country you've worked in. This means contacting the relevant pension authorities in your home country and any other countries where you've contributed. Understand the claiming process for each, as they often differ significantly. Consider the currency implications and how you'll receive payments. For instance, if you're receiving a foreign pension while living in Romania, or vice-versa, services like Wise can be instrumental in managing international money transfers efficiently, ensuring you get favorable exchange rates. Furthermore, tax implications are huge here. You'll need to understand how your combined pension income is taxed, both in Romania and potentially in your country of origin, especially given double taxation agreements. It might be wise to consult with a tax specialist or a service like Taxes for Expats who can navigate the complexities of international tax laws and help you file your annual returns, possibly including your Filing Your Annual Single Tax Return (Declarația Unică) in Romania: The Complete Walkthrough.
| Pension Pillar | Type | Mandatory/Voluntary | Funding Source | Key Features | Expat Relevance |
|---|---|---|---|---|---|
| Pillar I | Public, Pay-as-you-go | Mandatory | Social Insurance Contributions (CAS) from current workers | State-managed, collective fund, eligibility based on contribution period & age, benefits calculated by formula. | Totalization for EU citizens; bilateral agreements for some non-EU; foundation of local pension. |
| Pillar II | Mandatory Private | Mandatory (for eligible ages) | Portion of CAS contributions | Privately managed investment funds, individual accounts, capital accumulation, generally conservative investments. | Personal funds, portable in principle (at retirement), statements show individual growth, managed by entities like NN Pensii or BCR Pensii. |
| Pillar III | Voluntary Private | Voluntary | Personal contributions | Privately managed investment funds, tax deductions for contributions (up to annual limit), greater fund choice, flexible contributions. | Supplementary savings, tax efficient, helps bridge potential income gaps, provides more control over retirement investments. |
Maximizing Your Retirement Savings and Planning for the Future
Thinking about retirement from an expat perspective can feel overwhelming. You’re often balancing short-term goals with long-term financial security, all while navigating unfamiliar systems. However, with the right information and a proactive approach, you can build a robust retirement strategy that serves you wherever you choose to spend your golden years. It’s not just about what Romania provides, but how you integrate that with your broader financial universe.
The Importance of Early Planning and Diversification
If there’s one piece of advice I can give any expat, it’s to start planning early. The sooner you understand the Romanian pension system and how it fits into your overall financial picture, the more time you have to make adjustments, save more, and benefit from compound interest. Don’t wait until you’re close to retirement to start unraveling these complexities. Diversification is also key. Relying solely on Pillar I or even just the mandatory Pillars I and II might not be enough. Consider a mix of private pension funds (like Pillar III), personal investments, and perhaps property, to spread your risk and enhance your potential returns. A diversified portfolio is more resilient to market fluctuations and economic changes, giving you greater peace of mind. Remember that even small, consistent contributions to private savings can make a huge difference over decades.
Seeking Professional Financial Advice
Let’s be honest: financial planning, especially when it spans multiple countries and complex pension regulations, isn't something most of us can tackle entirely on our own. Seeking professional financial advice can be a game-changer. A good financial advisor, ideally one with experience working with expats and understanding international tax laws, can help you:
- Assess your current situation: Look at your existing pension entitlements, savings, and financial goals.
- Navigate cross-border complexities: Advise on totalization agreements, double taxation treaties, and the transferability of funds. This often involves understanding The Complete Guide to Taxes in Romania for Expats (2027) and how your global income is treated.
- Develop a personalized strategy: Recommend suitable investment vehicles, including Pillar III funds or other private savings options, tailored to your risk tolerance and objectives.
- Stay informed: Keep you updated on regulatory changes that could impact your retirement planning.
While there’s a cost associated with financial advice, the long-term benefits of having a clear, professionally guided strategy often far outweigh the fees. Don't underestimate the value of expertise when your financial future is at stake.
Tax Implications of Pension Income in Romania
Once you reach retirement, understanding how your pension income is taxed in Romania is crucial. Generally, pension income in Romania is subject to income tax. A flat income tax rate of 10% applies to pension income that exceeds a certain threshold (which is updated periodically, so always check the latest figures from ANAF). This means a portion of your pension might be tax-free, with the remainder taxed at the standard rate. However, this becomes particularly complex if you're receiving pensions from multiple countries. Romania has double taxation agreements with many nations to prevent you from being taxed twice on the same income. A tax residency certificate, which you can learn about in How Do I Get a Tax Residency Certificate in Romania, will be important here. You'll need to report all your income, both domestic and foreign, on your annual tax declaration. Failing to correctly declare foreign pension income to ANAF can lead to penalties. This is another area where professional guidance from an expert like Taxes for Expats can ensure compliance and potentially optimize your tax burden. For more general guidance on your financial obligations, remember to check out Understanding Income Tax (Impozit pe Venit) in Romania: The Full Expat Guide.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.