Understanding Pension Contributions and the Pillar System in Romania
Navigating the labyrinthine pension system in a foreign country can feel like trying to solve a Rubik's Cube blindfolded, especially when you're an expat already juggling new paperwork, cultural nuances, and sometimes even a new language. Romania's pension structure, with its distinct pillars, often leaves newcomers scratching their heads, wondering where their hard-earned contributions are actually going and what they can expect in return. This guide is here to shed light on Romania's pension landscape, demystifying the contributions, the various pillars, and what it all means for you as a foreigner building a life or a career here.
Deconstructing Romania's Multi-Pillar Pension System
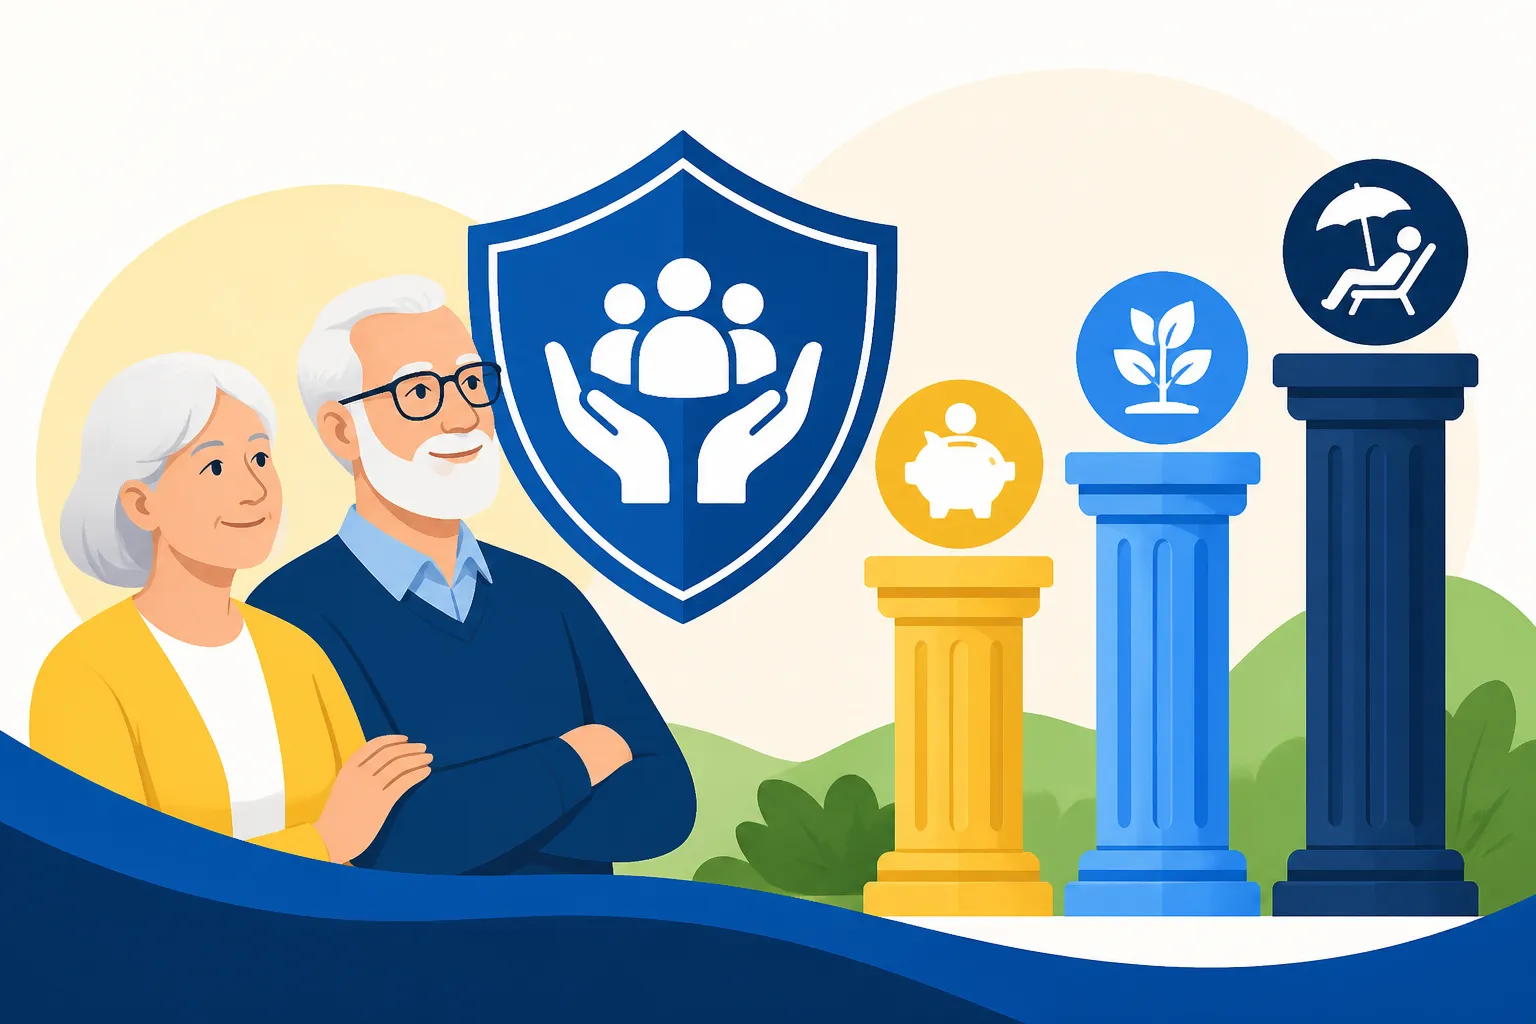
Romania, like many European countries, operates a multi-pillar pension system. This isn't just one big pot; it's a carefully structured approach designed to provide a more robust and diversified safety net for retirees. Understanding each pillar is crucial, as your contributions, eligibility, and the eventual benefits can differ significantly between them. For us expats, this means not just understanding that we contribute, but how and where those contributions are directed.
Pillar I: The State-Managed Public Pension (Sistemul Public de Pensii)
Think of Pillar I as the bedrock of Romania's pension system. This is the mandatory, pay-as-you-go public pension scheme, entirely managed by the state. Every single employee legally working in Romania, whether local or foreign, is automatically enrolled in and contributes to this pillar. It’s designed to provide a basic level of income in retirement, as well as disability and survivor benefits. Your contributions don't get squirrelled away in a personal account waiting for you; instead, they are immediately used to pay the pensions of current retirees.
The contributions to Pillar I are part of the larger social security contributions known as CAS (Contribuția la Asigurări Sociale). For most employees, this is a significant chunk of your gross salary – currently 25%. This 25% CAS payment is then further split, with a portion going to Pillar II if you're eligible, and the remainder funding Pillar I. Your employer is responsible for withholding this amount from your gross salary and remitting it to the state. You'll see this clearly reflected on your payslip, showing your individual contribution. It's a mandatory deduction, meaning you don't get a choice in opting out. For a deeper dive into all the social contributions, including health insurance (CASS), you might find our guide on Understanding Social Contributions (CAS and CASS) in Romania: The Full Guide particularly helpful. This first pillar is fundamental, and without a solid understanding of how it operates, it’s impossible to truly grasp the nuances of the entire Romanian pension framework.
Pillar II: Mandatory Private Pensions (Pilonul II)
While Pillar I is about collective solidarity, Pillar II introduces an element of individual capital accumulation. This is the mandatory private pension fund, established to diversify the risk of relying solely on the state pension. If you started contributing to the Romanian pension system after 2008 and are generally under the age of 35 (or under 45, depending on certain criteria and historical changes), a portion of your mandatory CAS contribution is diverted here, specifically earmarked for you. This doesn't mean you pay extra; it means a slice of that 25% CAS, which would otherwise go entirely to Pillar I, is redirected into a privately managed fund.
These funds are managed by private companies (often banks or insurance groups) under strict state supervision. They invest your contributions in various financial instruments with the goal of generating returns that will eventually augment your state pension. Unlike Pillar I, where your money is immediately paid out, your Pillar II contributions accumulate in your name. You can choose your Pillar II fund administrator, or one will be assigned to you if you don't make an active choice within a certain timeframe after starting employment. The performance of these funds varies, and you have the option to switch between administrators once a year. While the contributions are mandatory, the choice of fund administrator provides a degree of personal agency. It's a critical component for many younger expats, offering a more personalized and potentially higher-yielding addition to their retirement savings.
Pillar III: Voluntary Private Pensions (Pilonul III)
Pillar III is where personal initiative truly comes into play. This is an entirely voluntary private pension scheme, designed for those who wish to save beyond the mandatory Pillars I and II. It's an additional layer of financial security, offering more flexibility and typically higher potential returns, albeit with commensurately higher risk. Anyone can contribute to Pillar III, regardless of age or employment status, provided they have the means and desire for extra savings.
The allure of Pillar III for many expats lies in its potential for greater financial growth and the tax incentives offered by the Romanian state. Contributions to Pillar III are tax-deductible up to a certain annual limit, which can be an attractive benefit for those looking to optimize their tax burden while simultaneously saving for retirement. You select a private fund administrator, similar to Pillar II, but with a broader range of investment strategies and risk profiles available. These funds are usually managed by reputable financial institutions. Choosing a Pillar III fund involves a more active decision-making process, including assessing your risk tolerance and long-term financial goals. For many expats, especially those planning to remain in Romania for an extended period or who simply want more control over their retirement savings, Pillar III represents a valuable tool for augmenting their financial future. It's an option that provides peace of mind and the potential for a more comfortable retirement.
Who Contributes and How: Understanding Your Obligation as an Expat
Understanding that you contribute is one thing; knowing how and what your specific obligations are as an expat in Romania is another kettle of fish entirely. The rules can vary slightly depending on your employment status, your country of origin, and even how your work is structured. It’s not always straightforward, but knowing these details can save you a lot of headaches down the line.
Employees and Social Contributions (CAS)
If you're an employee with a standard Romanian employment contract, your pension contributions primarily fall under the umbrella of CAS (Contribuția la Asigurări Sociale). As mentioned earlier, this is a hefty 25% of your gross monthly salary. Your employer acts as the tax collector here – they are legally obliged to withhold this 25% directly from your paycheque and remit it to the state. This includes both the portion for Pillar I and the slice for Pillar II (if applicable to your age group). What you see deposited into your bank account is your net salary, after all these deductions, including CAS, income tax, and CASS (health insurance contributions).
This process is generally seamless for the employee, as the administrative burden falls on the employer. You don't have to actively do anything, other than ensuring your payslip accurately reflects these deductions. It’s always a good idea to understand Understanding Gross vs Net Salary and Payslips (Fluturaș) in Romania to cross-reference these amounts. For EU citizens, the situation is usually straightforward as Romania is part of the EU's social security coordination regulations. However, for non-EU citizens, bilateral social security agreements between Romania and your home country might come into play, potentially influencing where and how you contribute if you have dual employment or have recently moved. It's a complex area, but generally, if you're working under a Romanian contract, expect that 25% CAS deduction.
Self-Employed (PFA) and Micro-Enterprise Owners
Ah, the self-employed life! If you've chosen to venture into the world of being a PFA (Persoană Fizică Autorizată – authorized natural person) or you're running a micro-enterprise (SRL, but taxed under the micro-enterprise regime), your pension contributions operate quite differently from those of a standard employee. You become responsible for calculating, declaring, and paying your own social contributions, including CAS. This requires a much more proactive approach and a good understanding of Romanian tax law. You might find our guide on How to Register as a Sole Trader (PFA) in Romania helpful in understanding the initial setup.
For PFAs, the CAS contribution is determined based on your chosen income, but it cannot be lower than the contribution base derived from the minimum gross national salary. This means that even if you have a lower income in a given month, you still need to contribute a minimum amount towards your pension. This contribution is calculated at a 25% rate. The declaration and payment of these contributions are done through the notorious Declarația Unică, the single annual tax return that consolidates all your income and social contributions. This document is a beast for many expats, even for Romanians. You’ll need to declare your estimated income for the current year, and then true it up the following year. It’s absolutely essential to consult with an accountant to ensure you’re calculating and paying these correctly, as errors can lead to penalties. The nuances of How to File Your Annual Single Tax Return (Declarația Unică) in Romania are something you'll definitely want to master if you're self-employed here. Depending on your age when you started your PFA, you will also be obligated to contribute to Pillar II in the same manner as an employee, with a portion of your CAS being redirected there.
Special Cases: Digital Nomads, Remote Workers, and Cross-Border Situations
The rise of remote work and digital nomadism has added another layer of complexity to pension contributions, especially for expats in Romania. If you're living in Romania but working remotely for a company based in another country, your social security obligations are not always immediately clear. The general rule is that you contribute social security in the country where you perform your work, regardless of where your employer is located. However, there are significant exceptions.
For EU citizens, the A1 certificate is your best friend. If you're posted to Romania by an EU employer for a limited period, or if you normally work in two or more EU countries, the A1 certificate confirms which country's social security legislation applies to you, preventing double contributions. For non-EU citizens, it gets trickier. Bilateral social security agreements between Romania and your home country might dictate where you contribute. If no such agreement exists, you might find yourself in a situation where you're technically liable for contributions in both countries, or, conversely, not covered by any system adequately. This is where personalized advice becomes not just helpful, but absolutely vital. Consulting with a specialist in international taxation or using services like Taxes for Expats could save you from significant legal and financial woes. It's a situation where generic advice won't cut it, and understanding your specific circumstances is paramount to ensure compliance and adequate pension coverage.
| Pillar Name | Type | Mandatory/Voluntary | Primary Goal | Funding Mechanism | Key Benefits |
|---|---|---|---|---|---|
| Pillar I (Sistemul Public) | Public | Mandatory | Basic state-guaranteed pension | Pay-as-you-go (CAS portion) | Retirement, disability, survivor benefits |
| Pillar II (Pilonul II) | Private | Mandatory (age-based) | Complementary capital accumulation | Portion of mandatory CAS (privately invested) | Retirement income (annuity/lump sum) |
| Pillar III (Pilonul III) | Private | Voluntary | Additional savings, tax incentives | Voluntary contributions (privately invested) | Flexible retirement income, tax deductions |
Navigating the System: Registration, Transfers, and Benefits
Alright, you understand the pillars and how the money flows in. Now, let’s talk about the practicalities: how you actually get into this system, what happens if you need to move your pension, and ultimately, how you access your hard-earned benefits when the time comes. This is often where the bureaucratic hurdles for expats truly begin to feel real.
Registering for Pensions and Choosing Funds
For Pillar I, the state-managed public pension, registration is almost entirely automatic if you're legally employed in Romania. Once your employer reports your employment to the relevant authorities, you're in the system. You don't need to fill out separate forms or visit a pension office to get started with Pillar I. It's just part of being a registered worker.
Pillar II, the mandatory private pension, also has an element of automatic enrollment, but with a choice. If you fall into the eligible age group (typically under 35 or 45 when you first start contributing) and you don't actively choose a private fund administrator within a certain period after your first CAS contribution, one will be assigned to you by default. However, you have the right to choose an administrator from the list of approved private pension fund managers. The process usually involves contacting your chosen fund directly, filling out their application forms, and providing a copy of your ID and proof of social security number (CNP). For many expats, this is the first time they actively engage with the pension system beyond their payslip, so don't be afraid to ask questions. Having your CNP is essential for all official registrations, including pension matters, so make sure you've sorted out How to Get Your CNP (Personal Numeric Code) for Healthcare Access in Romania.
As for Pillar III, the voluntary private pension, the choice and registration process are entirely up to you. You'll need to research and select a private pension fund administrator that aligns with your financial goals and risk appetite. Once you've chosen, you simply contact them, complete their enrollment forms, and set up your contributions, which can often be done via direct debit from your bank account. They'll guide you through the specific documents required, which typically include your ID, CNP, and bank details. It’s a bit more proactive than the other pillars but also offers more control over your long-term savings strategy.
Transferring Pensions (Within Romania and Internationally)
The idea of transferring pensions can be quite complex, especially when crossing borders. Within Romania, transferring your Pillar II contributions between different private fund administrators is relatively straightforward. You are generally allowed to switch your Pillar II fund once every year, usually after a minimum period of holding your funds with the current administrator. The process involves contacting the new fund you wish to join; they will handle the transfer process with your previous fund administrator. There might be a small fee associated with the transfer, so always check with the funds involved.
International pension transfers, however, are a different beast entirely. For EU citizens, the beauty of EU social security coordination rules means that periods of insurance, employment, or residence completed in one member state are taken into account when calculating pension rights in another. This doesn't mean your pension pot physically moves with you; rather, each country you've worked in will pay a portion of your pension when you retire, based on your contributions there. Your contributions aren't "lost" when you move within the EU. For non-EU citizens, things are much more complicated. Romania has bilateral social security agreements with a limited number of countries. If your home country has such an agreement with Romania, it might simplify the process of aggregating contribution periods or even transferring certain types of funds. If there's no agreement, your contributions in Romania might only be accessible under Romanian law, and vice versa for your home country. This is a critical area for long-term planning, and often requires expert advice to ensure you don't inadvertently lose out on benefits. If you're mapping out your long-term future in Romania, understanding The Complete Guide to Working in Romania as a Foreigner (2027) touches upon such long-term implications.
Accessing Your Pension: Retirement, Early Retirement, and Other Benefits
The ultimate goal of all those contributions is to provide you with income when you need it most. Accessing your pension in Romania involves different processes for each pillar.
For Pillar I, the state pension, eligibility is based on reaching the statutory retirement age and having accumulated a minimum qualifying period of contributions. The standard retirement age in Romania is gradually increasing, so it’s always best to check the most current legislation. Once you meet these criteria, you apply to the local pension house (Casa de Pensii). The amount you receive depends on your contribution history, the points accumulated throughout your working life, and various other factors. This pillar also covers disability pensions (if you're unable to work due to health reasons) and survivor benefits for your dependents in the event of your death.
Pillar II funds are typically paid out when you reach the legal retirement age for Pillar I. The payment methods can vary but usually involve either a lump sum payment (if the accumulated amount is below a certain threshold), or regular payments over a period, often in the form of an annuity. The specific terms will be outlined by your chosen fund administrator. It's important to keep track of your statements from your Pillar II fund, as these show your accumulated capital and its performance over time.
Pillar III, being voluntary, offers more flexibility. The funds are generally accessible upon reaching the statutory retirement age for Pillar I, but some funds might allow earlier access under specific conditions (though penalties or tax implications might apply). The payout options are similar to Pillar II – lump sum or periodic payments, depending on the fund's rules and the amount accumulated. Because it's a personal savings plan, the terms are often clearer and more directly communicated by the fund administrator. For expats considering their financial future, knowing about Tax Residency in Romania: A Definitive Guide for Expats (2027) is crucial, as it impacts how your pension income will be taxed depending on where you reside when you start receiving payments.
Key Considerations and Challenges for Expats
Living in Romania as an expat is an adventure, but let's be honest, it comes with its unique set of challenges. When it comes to something as intricate as pension contributions and future planning, these challenges can feel amplified. It's not just about the numbers; it's about navigating a system in a new cultural and linguistic context.
Language Barriers and Bureaucracy
This is perhaps the biggest hurdle for many expats in Romania. The pension system, like most administrative facets of Romanian life, is deeply intertwined with bureaucracy, and much of it operates solely in Romanian. Forms are in Romanian, official communications are in Romanian, and often, the civil servants you'll interact with at public institutions might not speak English. This can lead to frustration, misunderstandings, and sometimes, outright despair. It’s not uncommon to leave an office feeling more confused than when you entered.
Validation of your frustration here is key: it's not you, it's the system. Patience is more than a virtue; it's a survival skill. Bringing a Romanian-speaking friend, colleague, or professional translator with you to any official pension-related appointments is highly recommended. Better yet, consider investing in some Romanian language lessons. Even basic conversational skills can make a monumental difference in your interactions. Platforms like iTalki, for example, connect you with native Romanian tutors who can help you grasp the basics or even delve into specific vocabulary related to administration and finance. The effort to learn a bit of the local language can significantly smooth out your experience when dealing with officialdom.
Long-Term Financial Planning and Tax Implications
For expats, pension planning in Romania isn't just about contributing; it's about how these contributions fit into your broader, often international, financial picture. Many expats are not planning to stay in Romania indefinitely, which adds a layer of complexity. What happens to your Pillar I and II contributions if you leave Romania before retirement age? Can you access them, or will they sit there until you're eligible, even if you're in another country? The answers depend on your nationality, where you move to, and whether any bilateral agreements exist.
Furthermore, the tax implications of receiving a pension can be complex. When you eventually start drawing your pension, whether from Pillar I, II, or III, its taxation will depend on your tax residency at that time and any double taxation agreements between Romania and your country of residence. This is a critical point where many expats can stumble. For instance, if you retire back to your home country, will Romania still tax your Romanian pension, and will your home country also tax it? Understanding The Complete Guide to Taxes in Romania for Expats (2027) is essential, but for specific pension income, professional financial advice tailored to your unique international circumstances is invaluable. You're not just dealing with Romanian tax law, but potentially the tax laws of your home country as well.
Understanding Statements and Monitoring Your Contributions
It’s one thing to make contributions; it’s another to know if they're actually being registered correctly and how your funds are performing. While Pillar I contributions are generally tracked by the state pension house, you won't typically receive regular statements for this pillar in the way you would for a private investment. You can request information about your contribution history, but it often involves a visit to the pension house or using the national online portal (if you have access and a digital certificate).
For Pillar II and III, however, you should receive regular statements from your chosen fund administrator. These statements will detail your contributions, the investment returns, management fees, and the current value of your accumulated capital. It's crucial to review these statements carefully to ensure your contributions are correctly processed and to monitor the performance of your fund. If you identify any discrepancies or have questions, contact your fund administrator immediately. Keep meticulous records of all your payslips, contribution receipts (especially if self-employed), and pension statements. These documents are your proof of contribution and will be vital when you eventually claim your pension benefits, especially if you move countries or need to sort out any administrative issues further down the line. It's a proactive step that can save you immense stress years from now.
Disclaimer
The information provided in this guide is intended for general informational purposes only and does not constitute legal, financial, or tax advice. While we strive to provide accurate and up-to-date information, pension laws and regulations in Romania are subject to change. Expats are strongly advised to consult with a qualified legal, financial, or tax professional for advice tailored to their specific individual circumstances before making any decisions related to their pension contributions or planning in Romania.